Medicare Help You Can Trust.
Helping you make confident, informed Medicare decisions since 2007.
The Ultimate SAN DIEGO Medicare
Your Step-by-Step Guide to Enrolling with Confidence
For SAN DIEGO CALIFORNIA residents turning 65 or retiring with Medicare ahead
Medicare decisions matter. San Diego healthcare landscape—with its diverse
neighborhoods, hospital systems, and provider networks—means your coverage needs to
fit your San Diego life, not just any Medicare plan.

The Ultimate San Diego Medicare Checklist
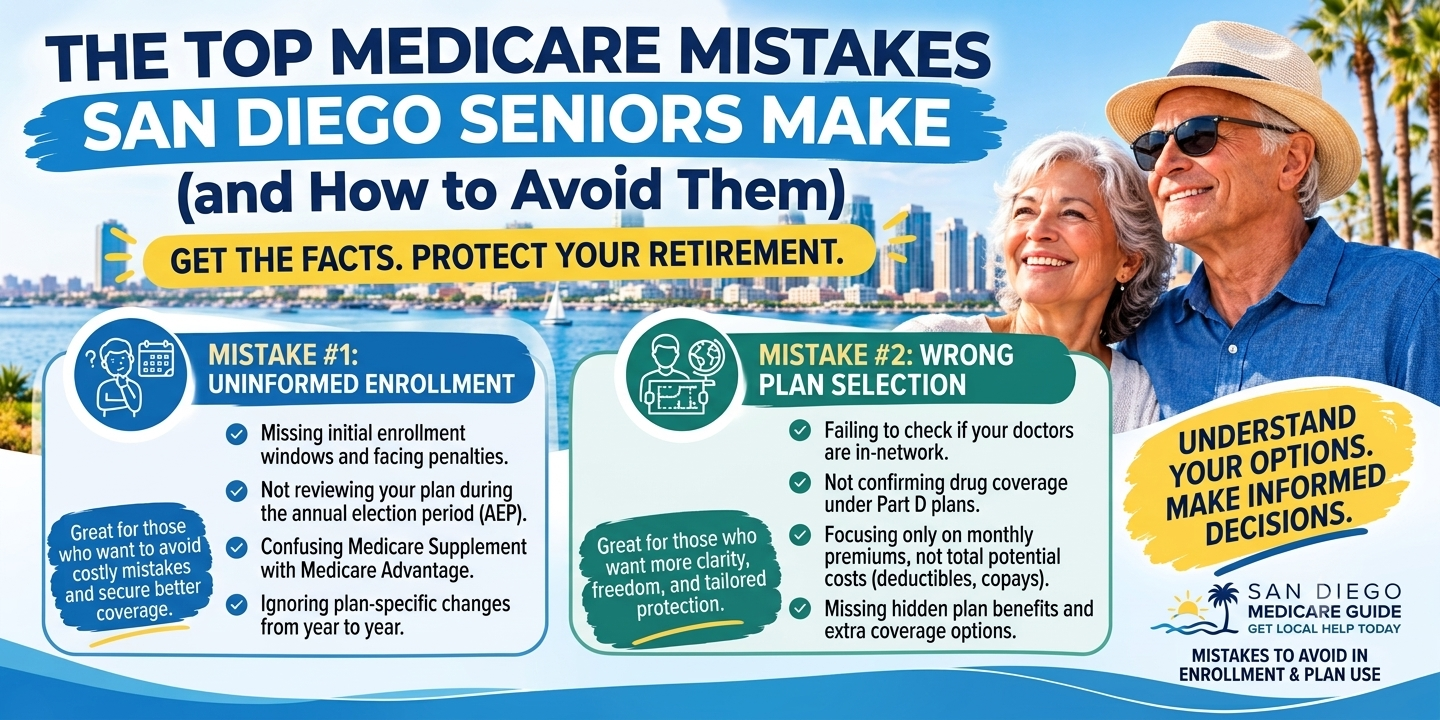
Your Step-by-Step Guide to Choosing Medicare Coverage in San Diego
For San Diego County residents who are turning 65, retiring, moving, or reviewing their current Medicare coverage.
Choosing Medicare coverage in San Diego involves more than comparing premiums and
extra benefits.
Your decision can affect whether you can continue seeing your doctors, use your preferred
hospital or healthcare system, fill your prescriptions at a convenient pharmacy, and
receive care when traveling outside California.
San Diego County includes several large healthcare systems and physician networks,
including:
- Kaiser Permanente
- UC San Diego Health
- Scripps Health
- Sharp HealthCare, including Sharp Memorial Hospital
Each Medicare Advantage plan can have its own provider network. A healthcare system
may participate with a plan while a particular physician, specialist, medical group, facility,
or office location does not.
This checklist can help Medicare shoppers in:
- San Diego
- La Jolla
- Point Loma
- Hillcrest
- Mission Valley
- North Park
- Clairemont
- Kearny Mesa
- Rancho Bernardo
- Poway
- Chula Vista
- Coronado
- La Mesa
- El Cajon
- Encinitas
- Carlsbad
- Oceanside
- San Marcos
- Escondido
- Del Mar
Use this guide to organize your information, avoid common enrollment mistakes, and
compare Medicare coverage based on how you actually receive healthcare throughout San Diego County.
TIMELINE: Know Your Medicare Enrollment Window
If You Are Turning 65
Your Medicare Initial Enrollment Period lasts seven months:
- Three months before the month you turn 65
- The month you turn 65
- Three months after the month you turn 65
Waiting too long to enroll could delay your coverage or result in late-enrollment penalties
unless you qualify for another enrollment period.
If You Are Retiring After 65
You may qualify for a Special Enrollment Period when your employment or qualifying
employer health coverage ends.
Medicare generally provides an eight-month Special Enrollment Period to enroll in Part B
after you stop working or lose job-based coverage, whichever happens first.
COBRA coverage does not extend that eight-month Medicare Part B enrollment period.
Before leaving employer coverage, ask your benefits department:
- When will my current coverage end?
- Is my coverage based on active employment?
- Do I need to enroll in Medicare Part A or Part B?
- Will retiree coverage or COBRA coordinate with Medicare?
- Does my employer prescription coverage qualify as creditable coverage?
Do not cancel employer coverage until you understand when your Medicare coverage will
begin.
STEP 1: Build Your San Diego Healthcare Profile
Before comparing Medicare plans, create a complete list of your healthcare providers.
Include:
- Primary care physician
- Cardiologist
- Endocrinologist
- Oncologist
- Orthopedic physician
- Dermatologist
- Physical therapist
- Mental health providers
- Medical equipment suppliers
- Any other providers you expect to continue seeing
For every provider, write down:
- Full name
- Specialty
- Office address
- Telephone number
- Practice or medical group
- Preferred hospital affiliation
If you’re still working:
- You may be able to delay Part B (confirm with HR)
Why This Matters
A physician may accept Original Medicare but not participate in every Medicare Advantage
plan.
Even when a hospital or healthcare system appears in a plan directory, verify the exact:
- Physician
- Medical group
- Facility
- Office location
- Plan network
Medicare Advantage members should also confirm participation with both the insurance company and the provider’s office.
A familiar hospital name does not necessarily mean every physician or medical group
connected with that hospital participates in the same Medicare Advantage network.
TEP 2: Identify Your Preferred San Diego Healthcare System
San Diego residents have several large healthcare systems available throughout the
county.
Understanding which system you prefer can be an important part of comparing Medicare
coverage.
Kaiser Permanente
Kaiser Permanente operates an integrated healthcare system in San Diego County. Kaiser Permanente San Diego Medical Center is located on Clairemont Mesa Boulevard, with Kaiser physicians, medical offices, pharmacies, and other facilities throughout the region.
Kaiser operates differently from many traditional healthcare networks because its health plan, physicians, facilities, and pharmacy services are closely integrated.
If you currently receive your care through Kaiser Permanente, ask:
- Can I continue seeing my current Kaiser doctors?
- Which Kaiser Medicare coverage options are available where I live?
- Which Kaiser facilities would I use?
- How does coverage work when I travel outside the Kaiser service area?
- What happens if I need care from a provider outside Kaiser?
Understanding these network rules is particularly important before changing from Kaiser to another Medicare option, or from another healthcare system into Kaiser.
UC San Diego Health
UC San Diego Health is an academic healthcare system with hospitals, specialists,
primary care physicians, and outpatient locations throughout San Diego County.
Major hospital locations include:
- Hillcrest Medical Center
- Jacobs Medical Center in La Jolla
- East Campus Medical Center
UC San Diego Health also operates specialty facilities and clinics throughout the region.
If you see a specialist through UC San Diego Health, verify both the physician and the
specific location before enrolling in a Medicare Advantage plan.
Scripps Health
Scripps Health is an integrated healthcare system serving communities throughout San
Diego County.
Scripps hospitals include:
- Scripps Memorial Hospital La Jolla
- Scripps Memorial Hospital Encinitas
- Scripps Green Hospital
- Scripps Mercy Hospital San Diego
- Scripps Mercy Hospital Chula Vista
Scripps also operates physician groups, specialty centers, clinics, and other healthcare
locations throughout the county.
If Scripps is important to you, verify your:
- Exact physician
- Medical group
- Hospital
- Specialty facility
- Medicare Advantage plan network
Do not assume every Scripps location participates with every Medicare plan.
Sharp HealthCare and Sharp Memorial Hospital
Sharp HealthCare operates hospitals, medical groups, physician offices, clinics, and
specialty facilities throughout San Diego County.
Sharp Memorial Hospital is located in central San Diego.
Other Sharp hospitals include:
- Sharp Chula Vista Medical Center
- Sharp Coronado Hospital
- Sharp Grossmont Hospital
- Sharp Tri-City Medical Center
- Other Sharp specialty facilities
If you prefer Sharp Memorial Hospital or another Sharp facility, verify your hospital and the
individual doctors you use.
Before enrolling in a Medicare Advantage plan, ask:
- Is my preferred hospital in-network?
- Is my doctor’s medical group included?
- Is my exact physician included?
- Is the outpatient facility I use included?
- Are my specialists in the same network?
- Can I use another San Diego healthcare system if needed?
- What happens if I receive nonemergency care outside the network?
- Never rely only on the hospital system’s name.
Verify the specific doctor, medical group, facility, office location, and Medicare plan.
STEP 3: Document Your Prescription Medications
Create a complete medication list before comparing Medicare plans.
Include:
- Medication name
- Dosage
- Quantity
- How often you take it
- Brand-name or generic version
- Preferred pharmacy
- Mail-order preference, if applicable
Then check:
- Is each medication on the plan’s formulary?
- Which drug tier applies?
- Is prior authorization required?
- Are there quantity limits?
- Does step therapy apply?
- Is your pharmacy preferred or standard?
- Would mail order change your cost?
STEP 4: Understand Your Two Main Medicare Paths
Path A: Original Medicare and Medicare Supplement
How It Works
- Original Medicare Part A and Part B provide your primary medical coverage.
- A Medicare Supplement plan may help pay certain deductibles, copayments, and
coinsurance. - You generally purchase a separate Part D prescription drug plan.
- You may use providers nationwide who accept Medicare.
This Path May Appeal to People Who:
- Want broader provider access
- Travel frequently
- Spend part of the year outside California
- See specialists across several healthcare systems
- Prefer more predictable medical expenses
Typical Considerations
- Separate monthly premiums may apply.
- Routine dental, vision, and hearing coverage generally is not included.
- Prescription coverage generally requires a separate Part D plan.
- Medicare Supplement availability and underwriting rules can depend on when you apply.
Path B: Medicare Advantage
How it works:
A private insurance company administers your Medicare Part A and Part B benefits.
Many Medicare Advantage plans also include:
- Part D prescription drug coverage
- Dental benefits
- Vision benefits
- Hearing benefits
- Fitness benefits
- Over-the-counter allowances
- Transportation benefits in some plans
Benefits, networks, copays, prior-authorization requirements, and plan availability vary.
Typical Considerations
- Many plans have low or $0 additional monthly premiums.
- You continue paying your Medicare Part B premium.
- Copays or coinsurance usually apply when you receive services.
- Provider networks may apply.
- Medicare Advantage plans include an annual maximum out-of-pocket limit for covered
Part A and Part B services.
STEP 5: Understand San Diego Medicare
Advantage Plan Types
HMO Plans
An HMO generally:
- Requires you to use in-network providers for nonemergency care
- May require you to select or work through a primary care physician
- May require referrals for specialists
- Usually does not cover routine out-of-network care
An HMO may be worth considering when your doctors, specialists, and preferred hospital
system participate in the same plan network.
PPO Plans
A PPO generally:
- Provides access to in-network and out-of-network providers
- Charges less when you use in-network providers
- Charges more for out-of-network care
- Does not require referrals to see specialists
A PPO may be useful when your doctors are spread across UC San Diego Health, Scripps
Health, Sharp HealthCare, or other healthcare systems.
Remember that additional flexibility does not mean every provider will accept your plan.
Always verify participation and understand what you could pay for out-of-network care.
D-SNP Plans
Dual Eligible Special Needs Plans are designed for people who qualify for both Medicare and Medi-Cal.
Depending on the plan, benefits may include:
What those ads may not explain:
- Care coordination
- Prescription drug coverage
- Transportation
- Dental and vision benefits
- Over-the-counter allowances
- Additional support services
STEP 6: Do Not Choose a Plan Based Only on an Advertisement
Medicare advertisements may emphasize:
- $0 monthly premiums
- Dental coverage
- Grocery or healthy-food benefits
- Transportation
- Fitness memberships
- Over-the-counter allowances
- Part B premium reductions
These benefits may be useful, but an advertisement may not explain:
- Whether your doctors are in-network
- Whether your preferred San Diego hospital is included
- Whether UC San Diego Health, Scripps, Sharp, or Kaiser works with the coverage you are
considering - Whether your prescriptions are covered
- What you could pay for hospital care
- What prior authorization rules apply
- Whether certain benefits have additional eligibility requirements
- How your coverage works outside San Diego County
Extra benefits are only one part of the decision.
Your doctors, hospitals, prescription medications, expected healthcare costs, and lifestyle
should also be reviewed.
STEP 7: Compare Your Out-of-Pocket Costs
Do not compare Medicare plans based only on the monthly premium.
Ask about the costs of healthcare services you are most likely to use.
Review:
- Primary care visits
- Specialist visits
- Diagnostic imaging
- MRI and CT scans
- Outpatient surgery
- Physical therapy
- Emergency room visits
- Ambulance services
- Inpatient hospital stays
- Skilled nursing care
- Durable medical equipment
- Prescription medications
- Annual maximum out-of-pocket limit
A $0-premium Medicare Advantage plan can still have copays, coinsurance, and other
costs when you receive care.
Consider both:
1. What will I pay each month?
2. What could I pay if I actually need healthcare?
If you regularly see specialists or expect surgery, diagnostic testing, physical therapy, or
hospital care, looking beyond the monthly premium can be especially important.
STEP 8: Think About Your San Diego Lifestyle
Your Medicare coverage should fit the way you live. Ask yourself:
- Do I travel outside California?
- Do I spend part of the year in another state?
- Do I travel to Mexico or internationally?
- Do I see doctors across several San Diego healthcare systems?
- How far am I willing to drive for an in-network provider?
- Would I prefer coordinated care through an HMO?
- Would I value the additional flexibility of a PPO?
- Do I prefer broader provider access through Original Medicare and a Medicare
Supplement? - Do I need dental, vision, hearing, or transportation benefits?
- Am I comfortable requesting referrals when required?
La Jolla and University City
Residents may receive care through UC San Diego Health, Scripps Memorial Hospital La
Jolla, Scripps Green Hospital, Sharp-affiliated physicians, and numerous specialty
providers throughout the area.
If your primary doctor is in one healthcare system but a specialist is in another, network
verification becomes particularly important.
Hillcrest, Mission Valley and Central San Diego
Residents may use UC San Diego Health’s Hillcrest facilities, Scripps Mercy Hospital San
Diego, Sharp HealthCare facilities, Kaiser Permanente, and independent medical groups
throughout central San Diego.
Having several nearby hospitals does not necessarily mean they are all available through
the same Medicare Advantage network.
Chula Vista and South Bay
Residents may receive care through:
- Sharp Chula Vista Medical Center
- Scripps Mercy Hospital Chula Vista
- Kaiser Permanente facilities
- Local physician and specialty groups
If you regularly travel north into central San Diego for specialists, consider both provider
network access and driving distance.
Encinitas, Carlsbad and Coastal North County
North County residents may receive care through Scripps Memorial Hospital Encinitas and
physicians located throughout the coastal communities.
Some people may also travel to La Jolla or central San Diego for specialty care.
Ask whether those providers are all available through the Medicare plan you are
considering.
STEP 9: Review Your Medicare Coverage Every Year
Your healthcare needs can change.
Medicare Advantage and Part D plans can change annually as well.
Review:
- Monthly premiums
- Provider networks
- Hospital participation
- Prescription formularies
- Pharmacy networks
- Copays and coinsurance
- Maximum out-of-pocket limits
- Prior-authorization requirements
- Dental, vision, and hearing benefits
- Transportation benefits
- Over-the-counter benefits
Also ask:
- Are my doctors still participating?
- Is my hospital still in-network?
- Did any of my prescriptions change tiers?
- Did my preferred pharmacy change?
- Have my healthcare needs changed?
Do not assume that the plan you have today will remain unchanged next year.
Questions to Ask Before Choosing a San Diego Medicare Plan
Bring these questions to your Medicare appointment:
- Are all my doctors in-network?
- Is my preferred hospital system included?
- Is my exact medical group included?
- Is my doctor’s specific office location included?
- Do I need referrals?
- Are my prescriptions covered?
- What will I pay at my pharmacy?
- Is my pharmacy preferred or standard?
- What will I pay for specialist visits?
- What might I pay for diagnostic imaging?
- What could I pay for outpatient surgery?
- What could I pay for an inpatient hospital stay?
- What is the annual maximum out-of-pocket limit?
- Is prior authorization required for services I regularly use?
- What happens if I receive healthcare outside California?
- What happens if I travel?
- Does the plan include dental coverage?
- Which dentists accept the dental network?
- Are any extra benefits subject to additional eligibility requirements?
- Can my spouse enroll in the same plan?
Your Medicare Appointment Checklist
Bring or prepare:
☐ Medicare card
☐ Social Security information, when needed
☐ Current insurance cards
☐ Complete doctor list
☐ Complete prescription medication list
☐ Preferred hospital or healthcare system
☐ Pharmacy information
☐ Employer or retiree coverage documents
☐ Medi-Cal information, if applicable
☐ Veterans coverage information, if applicable
☐ Written questions
☐ Travel and lifestyle information
Final Thoughts for San Diego Medicare Shoppers
Choosing Medicare coverage is not simply about finding a familiar insurance company or
the lowest monthly premium.
You are deciding:
- Which doctors you can see
- Which hospitals you can use
- How your prescriptions are covered
- What you may pay when you need healthcare
- How your coverage works when you travel
From La Jolla and Hillcrest to Chula Vista, Encinitas, Carlsbad, Escondido, San Marcos,
and communities throughout San Diego County, Medicare plan networks and benefits can
vary.
Take your time.
Ask questions.
Verify your doctors, hospitals, medications, pharmacy, and expected costs before
enrolling.
Need Help Comparing Medicare Plans in San Diego?
As your San Diego Medicare insurance advocate, Nolan and The Popel Insurance Group
can help you:
✓ Review your doctors and prescription medications
✓ Check access to Kaiser Permanente, UC San Diego Health, Scripps Health, Sharp
Memorial Hospital, Sharp HealthCare, and other local providers
✓ Compare Medicare Advantage HMO, PPO, and D-SNP plans
✓ Compare Original Medicare, Medicare Supplement, and Part D options
✓ Review premiums, copays, hospital costs, and prescription coverage
✓ Help you compare coverage based on your neighborhood, healthcare needs, and
lifestyle
The Popel Insurance Group

Nolan Popel
Schedule Your Medicare Consultation
- 30 Minute Consultation
- Phone or Zoom (see below)
- 100% Free